What is the market overview and industry significance of the Industrial Tow Tractors And Burden Carriers Market?
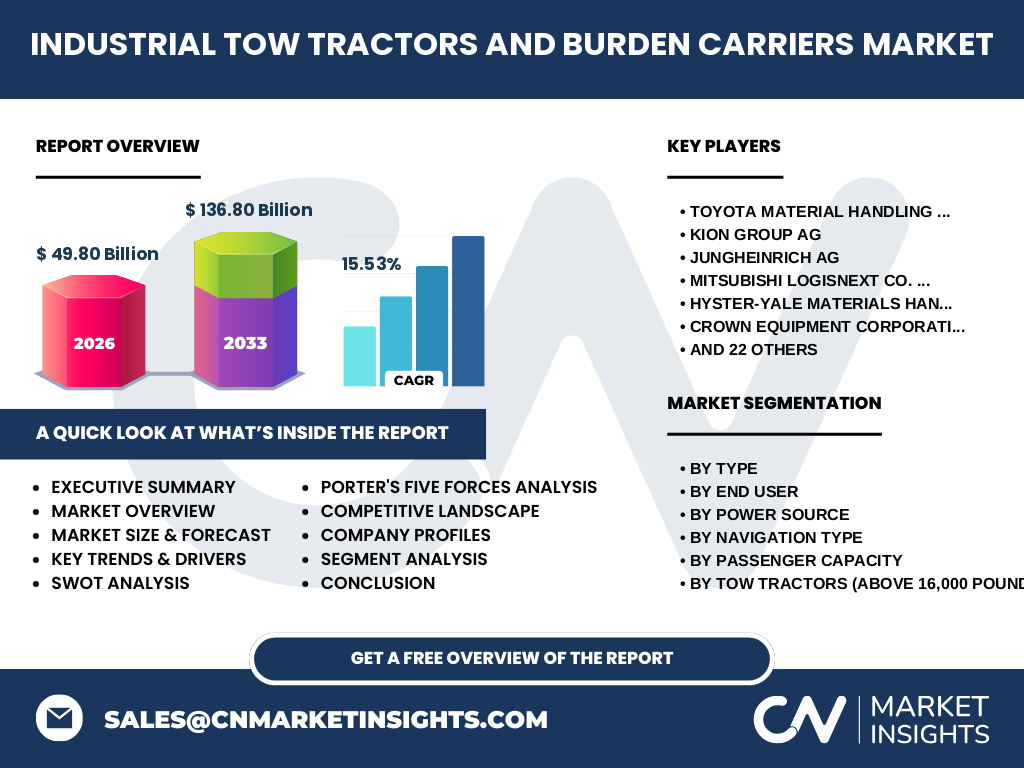
Our analysis indicates that the Industrial Tow Tractors And Burden Carriers Market is a vital pillar of intra-logistics, valued at 49.80 Billion in 2026. These specialized utility vehicles streamline horizontal transport across massive fulfillment hubs, manufacturing floors, and major aviation tarmac facilities, reducing reliance on manual material handling and mitigating workplace injury risks under strict OSHA compliance standards.
What are the key market drivers, restraints, challenges, and opportunities shaping the Industrial Tow Tractors And Burden Carriers Market?
Explosive e-commerce fulfillment demands serve as primary structural growth drivers, pushing fleets toward high-capacity configurations. However, stringent EPA emissions standards and supply chain bottlenecks for lithium-ion battery cells act as notable restraints. Opportunities abound in autonomous retrofits, helping logistics operators offset persistent warehouse labor shortages.
Emerging trends and growth patterns in the Industrial Tow Tractors And Burden Carriers Market
The market is witnessing a decisive pivot toward zero-emission lithium-ion electric power sources. Fleet operators increasingly demand Fully Automated Guided Vehicles (AGVs) equipped with LiDAR navigation to integrate seamlessly with warehouse execution software, dramatically minimizing transit times in high-throughput distribution hubs.
COVID-19 impact analysis and recovery trajectory for the Industrial Tow Tractors And Burden Carriers Market
Pandemic-era lockdowns initially caused severe supply chain disruptions and component shortages for traditional internal combustion models. Conversely, the subsequent surge in online retail accelerated long-term automation investments, driving an aggressive post-COVID recovery trajectory centered on contactless material transport and automated burden carrier fleets.
Competitive benchmarking and strategic dynamics in the Industrial Tow Tractors And Burden Carriers Market
Competitive intensity is high, characterized by a mix of legacy industrial giants like Toyota Material Handling Group, KION Group AG, and Jungheinrich AG, alongside specialized players such as Club Car LLC and Bradshaw Electric Vehicles Ltd. Strategic positioning increasingly relies on proprietary telematics and modular electrification packages.
Executive summary of key findings in the Industrial Tow Tractors And Burden Carriers Market
Driven by rapid warehouse automation and airport modernization projects, the Industrial Tow Tractors And Burden Carriers Market is poised for exceptional expansion. Our research projects robust market growth from 2027 to 2033, backed by a strong 15.53% CAGR that underscores a fundamental transformation in intra-logistics operations.
Market forecast and revenue trajectory from 2027 to 2033
The data suggests unprecedented financial momentum, with the market projected to surge from its 2026 baseline to reach an impressive 136.80 Billion by 2033. This exponential leap is fueled by widespread adoption of heavy-duty electric models across automotive manufacturing and global air cargo hubs.
Segmentation analysis across product types, end users, power sources, and navigation
Market segmentation covers diverse operational requirements: By Type spans Tow Tractors (Up To 12,000 Pounds to Above 16,000 Pounds) and Burden Carriers (Up To 2,000 Pounds to Above 3,500 Pounds). By End User includes Retail, Healthcare, Logistics, Manufacturing, and Aviation. Power sources feature Internal Combustion, Electric, and Hybrid, while Navigation ranges from Manual to Fully AGV systems.
Regional market analysis and geographic performance distribution
Geographic performance is heavily influenced by regional manufacturing output and logistics infrastructure density. North America and Europe dominate through early adoption of warehouse automation, while the Asia-Pacific region demonstrates the fastest growth rate, propelled by massive automotive manufacturing hubs in China, Japan, and India.
In-depth regional review of key high-growth markets
In North America, stringent workplace safety regulations and mega-warehouse developments drive high-capacity electric adoption. Meanwhile, European markets prioritize strict carbon reduction targets, forcing airports and manufacturing plants to rapidly transition from diesel-powered tow tractors to advanced electric fleet alternatives.
Company profiles and strategic market positioning
Industry leaders leverage distinct competitive moats. Toyota Material Handling Group and KION Group AG utilize global dealer networks to deploy diverse electric fleets. Meanwhile, niche innovators like Mototok International GmbH and MasterMover Ltd. specialize in remote-controlled, high-torque tuggers tailored for specialized aerospace and heavy industrial applications.
Porter's Five Forces analysis of the Industrial Tow Tractors And Burden Carriers Market
Bargaining power of buyers remains moderate to high due to numerous established equipment suppliers. However, threat of new entrants is constrained by high R&D costs for autonomous navigation tech and strict safety certifications required for heavy-duty industrial towing machinery operating near personnel.
SWOT analysis highlighting core industry attributes
Key strengths include robust vehicle durability and advanced telematics integration. Weaknesses involve high upfront capital expenditures for autonomous AGV units. Opportunities center on emerging micro-fulfillment centers, while threats stem from macroeconomic headwinds affecting industrial capital expenditure budgets.
Value chain analysis from raw materials to end-user deployment
The value chain begins with raw material sourcing for high-strength steel and lithium battery cells. Tier-1 component manufacturers supply critical drivetrains and hydraulic systems to OEMs like Crown Equipment Corporation and Hyster-Yale, who subsequently distribute through authorized dealers to end-users in aviation and logistics.
Investment insights and strategic high-potential focus areas
Investors should prioritize manufacturers scaling Fully Automated Guided Vehicles (AGVs) and proprietary fleet management software. High-margin opportunities exist in retrofitting legacy internal combustion fleets with modular electric powertrains to meet corporate net-zero carbon reduction mandates.
Conclusion and primary takeaways for industry stakeholders
The Industrial Tow Tractors And Burden Carriers Market represents a high-growth frontier within industrial automation. Stakeholders must embrace electrification and autonomy to capture market share as supply chains modernize to meet accelerated consumer and industrial throughput expectations.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by combining customs and trade registry data, primary qualitative interviews with C-suite logistics executives, and secondary macroeconomic indicators from global manufacturing indices to ensure absolute data integrity and predictive accuracy.
Scope of the report and operational coverage parameters
This comprehensive report evaluates global market dynamics for industrial tow tractors and burden carriers across specific weight thresholds, propulsion types, and navigation architectures. Geographic scope encompasses North America, Europe, Asia-Pacific, Latin America, and MEA, with historical baselines anchored around 2026.
Recent developments, strategic partnerships, and product launches
Recent industry momentum is defined by strategic joint ventures focused on autonomous navigation integration. Major equipment manufacturers have actively rolled out zero-emission, high-torque electric tow tractors designed specifically to comply with stringent zero-emission GSE mandates enacted at major international airports.